Construction projects need financial protection while buildings are taking shape. Suitable insurance helps manage repair costs when unexpected events affect unfinished structures. It also supports project owners who want to keep work moving toward completion. Understanding coverage options makes planning easier before work begins. Contractors can explore suitable coverage for their responsibilities with general contractors insurance from SOGO.
What Does Coverage Include?
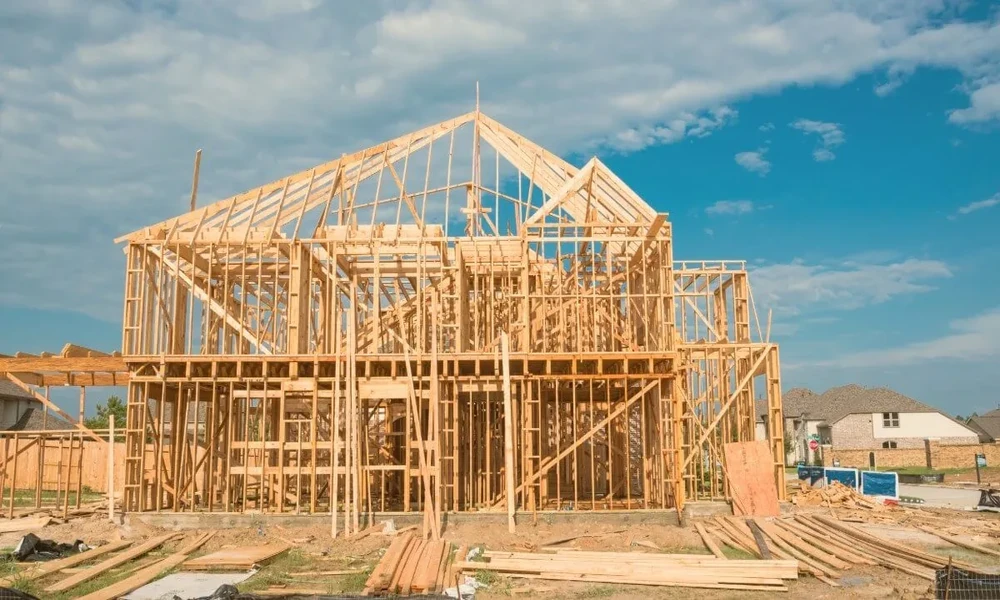
Builders risk insurance generally protects buildings under construction against covered physical losses during the building process. Protection may extend to supplies stored at the property or materials waiting for installation. The exact terms depend on the policy selected. Reviewing these details early helps project owners understand the support available throughout each construction stage.
- Structural components installed during ongoing building work.
- Construction supplies kept within approved storage areas.
- Temporary structures included under agreed policy terms.
- Building materials awaiting placement during scheduled work.
- Repair expenses resulting from covered physical damage.
Which Risks Require Protection?
Active construction can expose unfinished structures to several types of damage. Fire, severe weather, theft of covered materials, or accidental damage may affect schedules and budgets. Appropriate insurance helps address eligible losses according to the policy terms.
A careful assessment can help identify relevant protection needs. Important considerations include:
- Estimated value of completed work and stored supplies.
- Local weather conditions affecting the construction schedule.
- Security measures used to protect building materials.
- Project duration from initial work through completion.
- Contract terms defining financial responsibilities among involved parties.
How Can Contractors Plan Coverage?
Contractors can begin by preparing accurate project details before requesting a policy. Clear records help insurers assess the work and determine suitable coverage limits. By choosing general contractors insurance from SOGO, contractors can explore protection options suited to their business responsibilities. Reviewing policy terms with an insurance professional supports informed decisions during project planning.
- Record projected building costs before work starts.
- Keep purchase receipts for important construction supplies.
- Confirm coverage dates match the planned schedule.
- Review payment duties assigned under project agreements.
- Update project details when major changes occur.
What Affects Policy Costs?
Policy pricing often depends on the total project value, construction methods, and expected duration. The building location can also influence the level of risk considered during assessment. Higher coverage limits may increase premiums. Providing complete details helps insurers estimate suitable terms for the specific project. Comparing written quotations allows contractors to evaluate available options carefully.
How Does Coverage Support Completion?
Suitable protection helps project owners respond financially when covered damage interrupts planned work. A clear claims process can support repair planning while teams organise the next steps. Keeping photographs, receipts and progress records makes it easier to explain a loss. Regular reviews also help maintain suitable protection as the project develops toward handover.
FAQ
What does builders risk coverage usually protect during construction projects?
It generally covers eligible physical damage to unfinished buildings and supplies.
When should contractors arrange protection for active construction work?
Arrange suitable coverage before construction begins or materials arrive on site.
Can policy terms change during a building project?
Yes, insurers may revise terms when project details or values change.
