For Luxembourg holding and financing structures, the debate around “ATAD 3” has changed significantly. The proposed EU Unshell Directive was intended to create a more harmonised framework for identifying entities with insufficient substance, but the proposal was ultimately abandoned. That does not make substance less important.
The focus instead returns to the rules already in force: anti-abuse provisions, beneficial ownership, tax-residence analysis, the principal purpose test where relevant, and the factual question of where a company is genuinely managed. In that environment, governance matters more than a checklist of formal indicators.
ATAD 3 Did Not Become the New Substance Test
The phrase “after ATAD 3” should therefore be understood carefully. Luxembourg companies are not currently subject to a harmonised EU Unshell test created by that proposal.
Substance continues to be assessed through the existing legal framework and the facts of each case. Companies should not build governance around thresholds or indicators from a proposal that never entered into force.
The practical question remains whether the entity has a credible economic and decision-making presence consistent with the functions it performs.
A Registered Office Is Not Effective Management
A Luxembourg address is necessary for a Luxembourg company, but an address alone does not demonstrate where management occurs.
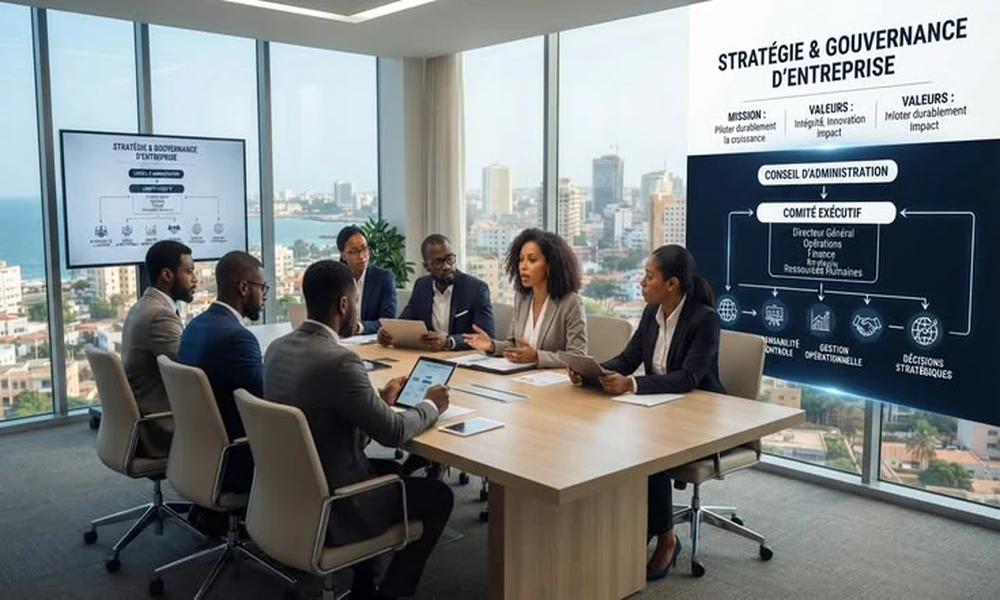
Tax-residence and anti-abuse analysis can look at where important decisions are taken, who has authority to take them and whether directors genuinely exercise that authority.
A board that meets formally in Luxembourg but simply approves instructions developed elsewhere may create a different factual picture from a board that reviews information, challenges proposals and makes decisions locally.
This is why “mind and management” remains central to the substance discussion.
Governance Creates the Evidence Behind Substance
Financial Services Luxembourg’s economic-substance framework emphasises real decision-making, competent directors, local governance, accounting and appropriate operational means rather than a universal numerical checklist.
That reflects an important point: substance is not proved by one document or one director. It is supported by a coherent body of evidence showing how the company actually operates.
Board packs, minutes, local accounting records, banking activity and documented approval processes can all contribute when they reflect genuine behaviour.
Beneficial Ownership Is a Separate Question
Substance should not be confused with beneficial ownership.
A company may have directors, premises and accounting records while still facing questions about whether it is the genuine recipient of income for treaty or directive purposes.
Beneficial ownership analysis focuses on the economic entitlement to income and the recipient’s discretion over it. This can be relevant for holding and financing structures receiving dividends, interest or royalties.
Governance can support that analysis, but formal governance alone cannot determine the outcome.
The PPT Brings Purpose Into the Analysis
For treaty structures, the principal purpose test can also matter.
The PPT can deny treaty benefits where obtaining those benefits was one of the principal purposes of an arrangement or transaction, unless granting the benefit would remain consistent with the object and purpose of the relevant treaty provisions.
A Luxembourg structure should therefore be able to explain its commercial and organisational rationale beyond the availability of a tax advantage.
Documentation should address why the entity exists, what functions it performs and how its governance supports those functions.
Participation Exemption Requires More Than Formal Ownership
For SOPARFIs and other holding structures, the Luxembourg participation exemption remains important where the statutory conditions are satisfied.
But a structure relying on exemption or treaty benefits may also face anti-abuse scrutiny.
The relevant question is not whether the company can produce a checklist showing a local address, bank account and director. It is whether the wider facts support the position that the entity genuinely holds, manages and bears the risks associated with its investments.
Governance Records Must Match Reality
Minutes prepared after decisions have effectively been made elsewhere provide limited support.
Strong governance requires directors to receive information before meetings, consider alternatives, manage conflicts and document the reasons for significant decisions.
This does not mean every operational decision must be taken by the board. It means the company’s actual decision-making process should match the governance model presented in its records.
For cross-border groups, consistency between legal documents, accounting records, banking arrangements and board behaviour becomes especially important.
Conclusion
The abandonment of ATAD 3 did not remove the substance question from Luxembourg corporate structures. It removed the prospect of one particular harmonised EU test.
What remains is a facts-and-circumstances analysis under existing anti-abuse, tax-residence and beneficial-ownership rules. That is why governance has become more important than checklists.
A defensible Luxembourg structure is built through genuine decision-making, competent oversight, coherent documentation and an operational reality that supports the tax and corporate position the company claims to have.
